How to Buy a Home in Vancouver, WA: Step-by-Step Guide
How to Buy a Home in Vancouver, WA: Step-by-Step Guide
From budgeting and pre-approval to closing day — the seven steps that actually get you from house hunting to holding the keys.
Buying a home in Vancouver, WA comes down to seven steps: get your budget and mortgage pre-approval sorted first, research the local market and neighborhoods, partner with a local agent, build a clear must-have/nice-to-have list, make a competitive offer once you find the right home, complete a professional inspection, and close. Most Vancouver closings take 30–45 days from offer acceptance. The single biggest head start: get pre-approved before you start touring homes, not after.
Owning your dream home is an exciting milestone, and if you're ready to make that dream a reality, buying a home in Vancouver, WA is a smart choice. Whether you're a first-time homebuyer in Vancouver or looking to upgrade, having a solid plan makes the process much smoother. Navigating the Vancouver, WA real estate market might seem overwhelming, but with a clear checklist, you'll be well-prepared to find the home that fits your life and budget.
In this guide, I'll walk you through everything you need to know about buying a home in Vancouver, WA—from setting your budget and researching homes for sale in Vancouver, WA, to partnering with a trusted local agent, making competitive offers, home inspections, and closing the deal.
Step 1: Understand Your Budget and Financing Options
The foundation everything else is built on
Owning your dream home begins with a clear understanding of your financial situation. Before you dive into house hunting, evaluate your budget carefully so you know what you can realistically afford.
Start by reviewing your savings, monthly income, debts, and other financial obligations. Calculate your comfortable monthly payment range, considering not just the mortgage but also property taxes, insurance, and maintenance costs.
Mortgage Pre-Approval: Your Key to a Strong Offer
Pre-approval involves an in-depth review of your finances by a lender, resulting in a conditional loan commitment. Unlike pre-qualification, it gives you a clear picture of your purchasing power and strengthens your offer in the eyes of sellers.
Lenders in Vancouver, WA offer various loan programs—FHA, VA, or conventional—tailored to different buyer needs. With pre-approval in hand, you'll be positioned as a serious buyer ready to compete in the local market.
Step 2: Research the Vancouver, WA Real Estate Market
Know the neighborhoods before you start touring
Understanding the Vancouver, WA real estate market is crucial to finding a home that fits your lifestyle and budget. Start by exploring different neighborhoods to identify which areas align with your priorities—schools, parks, or your commute.
Use online listings and mobile apps to get a feel for available properties and asking prices. Pay attention to how long homes stay on market and the price range across property types. Attend open houses and connect with a local agent who has firsthand knowledge of Vancouver's market dynamics.
Step 3: Partner with an Experienced Real Estate Agent
Your guide, advocate, and negotiator
Buying a home in Vancouver, WA can be a complex process, but a knowledgeable agent makes a real difference. A local agent understands the nuances of the market—neighborhood trends, pricing strategies, and which homes meet your must-haves and nice-to-haves.
Your agent will coordinate property viewings, explain contract details, and assist with negotiations to help you get the best deal, while managing timelines and contingencies to keep your purchase on track.
Step 4: Create a List of Must-Haves and Nice-to-Haves
Defining what you actually want before you start looking
Start with a checklist split into two categories: Must-Haves (non-negotiables like bedroom count, commute distance, or a specific neighborhood) and Nice-to-Haves (a large backyard, updated kitchen, or a soaking tub—great but not deal-breakers).
The Rule of Two: Price, Location, Condition
Understanding this trade-off helps you make practical decisions as you weigh your list. Stay flexible on the "nice-to-haves"—sometimes a property surprises you in all the right ways even when it's missing one.
Step 5: Make a Competitive Offer
Standing out once you've found the one
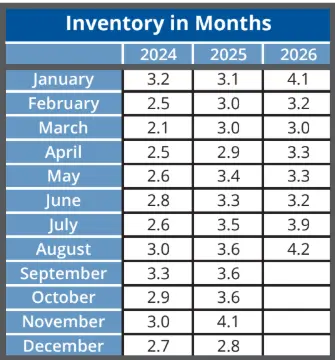
Your offer strategy depends heavily on current local conditions. In a seller's market, demand exceeds supply—you might need to offer above asking, waive some contingencies, or include an escalation clause. In a buyer's market, you'll often have more leverage to negotiate on price, closing costs, or repairs.
Your agent will run a comparative market analysis (CMA) to help structure your offer competitively. Beyond price, a few ways to strengthen your offer:
Step 6: Conduct a Home Inspection
Don't skip this once your offer is accepted
Even if a home looks perfect on the surface, underlying issues can go unnoticed. A licensed inspector will thoroughly examine the roof and attic, electrical and plumbing systems, HVAC, foundation and drainage, appliances and fixtures, and check for mold, pests, and other hazards.
After the inspection, you have three paths: negotiate repairs or credits toward closing costs, renegotiate the price for major problems, or walk away within your inspection contingency period if serious defects turn up. Your agent will help you review the report and decide the best path forward.
Step 7: Close on Your Dream Home
The final step—officially transferring ownership
Closing typically includes a final walkthrough to confirm the property's condition, reviewing and signing documents (mortgage agreement, deed, closing disclosures, title transfer), paying closing costs, funding the loan, and finally receiving your keys.
Most closings in Vancouver take 30–45 days from offer acceptance, though timelines vary based on lender requirements and contingencies. Your agent and loan officer will keep you informed every step of the way.
Buying in Vancouver, WA? Start Here
Frequently Asked Questions
Common home-buying questions, answered
What is the 30/30/3 rule for home buying?
What are the 4 C's when buying a home?
Is $10,000 enough for a down payment on a house?
What are the three C's of home buying?
Can I afford a $700k house with a $100k salary?
What is the 33% mortgage rule?
What habit lowers your credit score?
What are the 5 phases of buying a home?
How much house can I afford if I make $70,000 a year?
Ready to Start House Hunting in Vancouver, WA?
Sign up for my monthly newsletter for expert advice, local market updates, and insider knowledge on the best ways to thrive in this unique region.
Join My Newsletter Book a Buyer Discovery SessionCategories
Recent Posts
GET MORE INFORMATION
Cassandra Marks
Realtor, Licensed in OR & WA License ID: 201225764
Realtor, Licensed in OR & WA License ID: 201225764